
The dramatic swings in New Zealand's property market in recent years have been extremely challenging for first-home buyers needing a home of their own. After the first pandemic lockdown in 2020, the property market surged, prices soared and the deposits required of first-home buyers rose accordingly...
{ad}
The property market has turned this year, with house prices declining steadily. Data from property valuation company CoreLogic shows that in cities with particularly steep falls, such as Wellington and Auckland, prices are now more than 15% below their peaks around November last year. CoreLogic's latest House Price Index (HPI) shows that August marked the fifth consecutive month of declining average residential property values. It was also the first month since November 2021 in which New Zealand's average house price fell below NZ$1,000,000. Average values fell 1.8% in August, compared with 0.9% in July. Analysts say prices are continuing to fall and the pace of decline is accelerating. These substantial falls mean many first-home buyers who purchased at the market peak late last year may already be in negative equity, with mortgage balances exceeding their properties' current market values.
Meanwhile, mortgage interest rates have continued rising over the past year, with one-year fixed rates climbing rapidly from a low of around 2% to 5%. According to CoreLogic data, before July this year, 45% of borrowers had less than a year remaining on their fixed mortgage terms. This means many first-home buyers face the risk of a substantial increase in their mortgage interest payments.
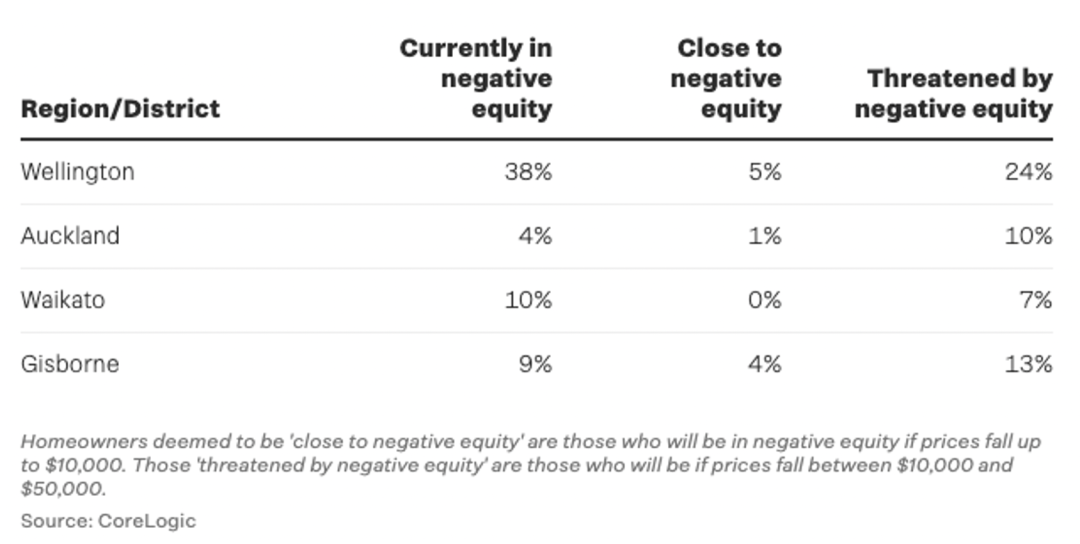
2021: proportion of homeowners in high-risk areas who bought during the year's final three months and are in or near negative equity
With first-home buyers facing such significant pressures, Stuff recently interviewed several people in Wellington, Auckland and Christchurch who had bought their first homes not long ago, asking how they really felt about their purchases.
Interviewee 1: Wellington first-home buyer Harrison Vaughan
Property manager Harrison Vaughan bought his first home in Wellington's Johnsonville in November last year, at the height of the market. Amid fierce competition, he paid NZ$930,000 for a three-bedroom house measuring 500 square metres. The median house price in the wider Wellington region was then NZ$962,500, so he was very happy with the NZ$930,000 price. Now, however, homes.co.nz estimates the property is worth just NZ$890,000. Vaughan openly admits the loss in value makes him somewhat uneasy. He plans to hold the property long term, believing prices will recover steadily after the current downturn.
His second concern is that the decline in value could prevent him from borrowing more from the bank to renovate the bathroom and kitchen. That would mean finding funds elsewhere or postponing the work. One reassuring factor is that when he signed his mortgage agreement, he chose a three-year fixed rate of 3.2%, easing much of the pressure. Had he chosen a one-year fixed rate, he would soon be facing rates above 5%, forcing major changes to his lifestyle and spending. Overall, he says owning his own home is still worthwhile, allowing him to leave long-term renting behind. Although he cannot predict what will happen in the property market, his home gives him greater security, and as long as he can afford the mortgage, he will not go bankrupt.
Interviewee 2: Auckland first-home buyer Sophie Lawson
The Lawsons, an Auckland couple, bought their first home on the Te Atatu Peninsula in March last year. Sophie Lawson said they felt very fortunate to have secured a home they loved before the market became even more frenzied. They love their property, which is just a 5-minute drive from the motorway, making it convenient to get anywhere. They had grown tired of renting. Falling house prices could leave many people in negative equity, but they are not worried, believing their property's value has stabilised rather than continued falling. Sophie Lawson said its value rose significantly over roughly the 9 months after purchase. Although they paid NZ$800,000, the home is now valued at NZ$1,000,000. They are confident it will appreciate over the long term and intend to sell at a suitable time to realise a capital gain.
They felt pressure on their household finances when they recently refixed their mortgage, with the rate rising from 3.2% to 4.72%. However, they believe this still seems a very good rate compared with the roughly 20% paid by their parents' generation in the 80s of the 20th century. Lawson firmly believes owning a home is worthwhile: they are now building wealth for their own future, rather than paying rent to help a landlord repay a mortgage.
Interviewee 3: Auckland first-home apartment buyer Daniel Steele
Daniel Steele is another Auckland first-home buyer. A few weeks ago, he moved into an apartment in Auckland's CBD that cost him NZ$410,000. The 21-year-old began saving for a home when he entered the workforce. He said he could have waited longer and saved a larger deposit, perhaps allowing him to buy a bigger property, but uncertainty in the market in recent years prompted him to act immediately. An apartment was not his first choice, but with a deposit of just NZ$83,000, his options were limited. Although taking on a mortgage at a young age brings considerable pressure, he sees the apartment as a starter home. He is delighted to be a homeowner and does not regret his decision.
Buying recently meant he missed out on last year's exceptionally low interest rates. He said his mortgage was split into two portions, with most fixed at 5.29% and the remainder on a floating rate of 6%. He accepts the current high rates calmly.
Interviewee 4: Christchurch first-home buyer Maeve Deacon
Christchurch's Maeve Deacon and her younger sister received the keys to their new home at the end of July this year. Their two-bedroom unit in Linwood, with a garden and garage, cost NZ$485,000. The sisters had spent years living frugally and saving hard for the deposit. They said the home did not currently need a complete renovation, but they hoped to decorate it to their taste while adding value to cushion against falling house prices. They see choosing the length of a fixed mortgage term as something of a gamble and have recently refixed for a year at 4.99%. Maeve said that although the property market may fluctuate, they take comfort in finally owning a home rather than renting, and the property gives both sisters a strong sense of security.